Finance & Money
Why We’re Maxing Out Our 401(k) — And Why Panama Is Part of the Same Plan
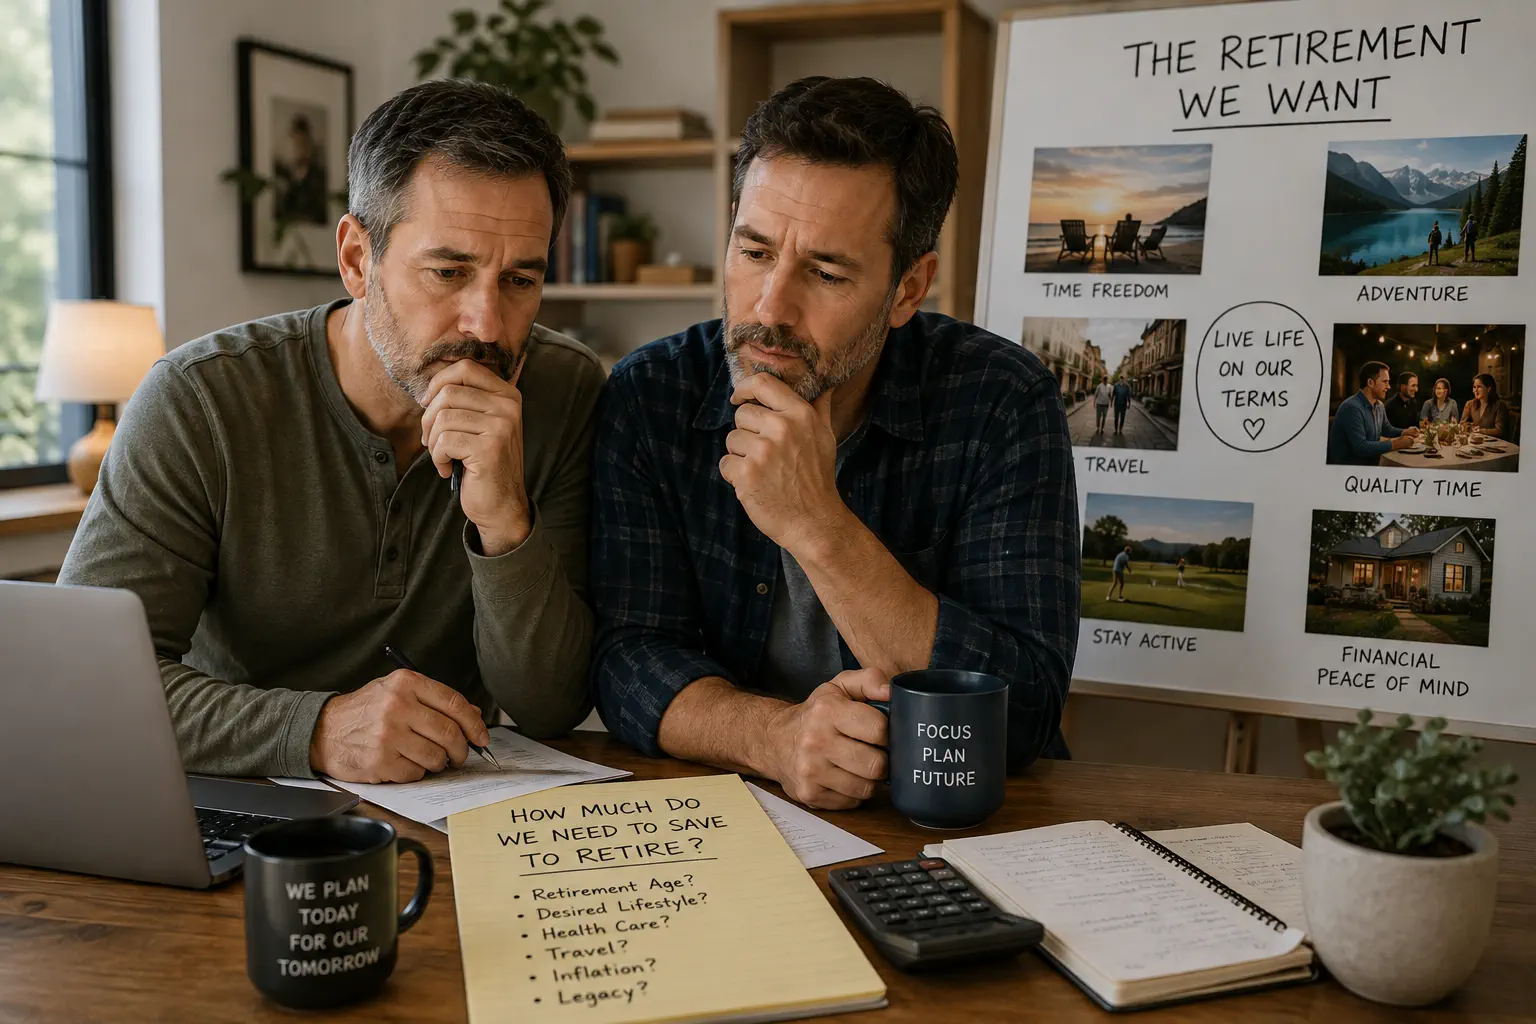
A new retiree survey found that most people wish they’d saved earlier and started sooner. It confirmed something we’d already been doing since coming back from Spain with our retirement accounts nearly empty — here’s the math, and how relocating fits into it.
 Brian & Kent · GayExpatsPanama.com · Updated August 2026
A Tampa Bay Times piece caught our eye this past Sunday: most Americans retire earlier than they planned, and most of them wish they’d saved more before it happened. The article was built on a new TIAA Institute study. We’ve been maxing out Kent’s 401(k) contribution since we came back from Spain with our retirement accounts close to empty — a decision that takes a real bite out of his take-home pay every month — and reading the data felt less like discovering something new and more like getting confirmation we weren’t overreacting.
This article is about two things that we think belong in the same conversation and rarely are: how aggressively you should be saving for retirement while you’re still working, and where you plan to spend that retirement. For most Americans, those are separate topics — a 401(k) conversation and a bucket-list conversation. For anyone seriously considering retiring abroad, they’re the same spreadsheet.
The Report That Prompted This
The TIAA Institute released a study in July 2026 called Bridging the Gaps in Retirement Expectations, surveying roughly 1,600 American adults ages 22 to 75. The headline numbers are stark: 76% of current retirees say they regret not starting to save earlier in life, and 71% wish they had saved more overall. Those aren’t close calls — that’s three out of four people looking back and telling researchers they got the timing wrong.
The regrets went beyond savings amounts. Roughly half of respondents said they regretted not having clear retirement goals, not planning for healthcare and long-term care costs, or not preparing for a late-career disruption — a layoff, a health event, a caregiving responsibility. And more than half — 51% — said they had left the workforce for over a year at some point due to something they didn’t plan for.
The study’s average respondent retired at 57. Workers who haven’t retired yet, surveyed in the same study, expect to retire at 62 — five years later. That gap is the whole story. As Surya Kolluri, head of the TIAA Institute, put it, what happens today will define the retirement you experience tomorrow.
TIAA Institute Study — Key Findings (July 2026)
Retirement Rarely Arrives on Schedule
Most people quietly plan around three ages, whether or not they’ve ever written it down: 62, when you first become eligible for Social Security; 65, when Medicare coverage starts; and 67, full retirement age for anyone born in 1960 or later, when Social Security pays out at 100% instead of a reduced early-claiming amount. It’s a tidy framework, and it assumes something that turns out to be true for barely more than 40% of retirees — that you get to choose when you stop working.
The more common pattern, according to this and prior research from EBRI and Transamerica, is that retirement arrives via a layoff, a round of corporate restructuring, or a health event in your household. Picture someone planning to work to 65. At 60, they’re laid off. The job search drags on. At 62 they’re still unemployed, technically eligible for Social Security but taking a permanently reduced benefit if they claim early out of necessity. They’re three years from Medicare and paying full price for health insurance in the meantime. And the five years of 401(k) contributions and employer match they had budgeted on their spreadsheet simply never happened — not because they changed their mind, but because the paycheck that would have funded them stopped first.
The Math Behind an Early Layoff
Five lost years of contributions doesn’t just mean five years of missed deposits. It means five years of missed employer match, five years of missed compounding on money that would have been invested a decade or more before retirement, and — if the gap forces early Social Security claiming — a permanently reduced monthly benefit for the rest of your life. The disruption compounds in both directions at once.
We don’t know whether the “retiring earlier than planned” trend in the TIAA data is mostly voluntary or mostly involuntary, and the report itself doesn’t fully separate the two. What is clear is that roughly half of respondents cited an unplanned late-career disruption, not a deliberate early-retirement choice. That distinction matters less than you’d think for the purposes of this article, though — the planning response is the same either way. If you can’t control when retirement starts, the only lever you fully control is how ready you are for it whenever it does.
Why We Started Maxing Out Kent’s 401(k)
We’re not writing this from a position of having always gotten it right. When we came back to the U.S. after closing our bar in Spain, our retirement accounts were close to empty — we’d been living on the business, not building savings on top of it. That’s the version of “starting over in your 50s” nobody puts on a postcard.
Since then, we’ve made maximizing Kent’s 401(k) contribution a fixed, non-negotiable line item, not a “whatever’s left over” afterthought. For 2026, the IRS allows up to $24,500 in employee contributions to a 401(k), with an additional $8,000 catch-up contribution available starting at age 50 (or up to $11,250 for savers who turn 60 through 63 this year). Contributing at that level takes a real, felt-in-the-monthly-budget chunk out of Kent’s take-home pay. We’ve adjusted other spending to make it work. That trade-off is the entire point of this section: it should hurt a little now, on purpose, because the alternative — catching up later, or not catching up at all — costs far more.
The Uncomfortable Truth About “Maxing Out”
Every dollar you contribute in your 50s has less time to compound than a dollar contributed in your 30s. That’s exactly why the response to a late start isn’t “give up and hope Social Security covers it” — it’s contributing more aggressively than you’d otherwise choose to, for as many years as you have left before you actually need the money. The TIAA data backs this up directly: the regret isn’t about the account existing, it’s about not funding it sooner or harder.
The Real Cost of Staying in Florida
The savings side of this is only half the plan. The other half is what your money has to cover once you stop earning it — and that’s where relocating enters the picture, because where you live in retirement is one of the largest controllable variables in the entire equation.
We live in St. Petersburg, and the numbers here have gotten genuinely alarming. Florida’s average homeowners insurance premium reached roughly $8,292 in 2025 — an 18% jump in a single year, and about two to three times the national average. That’s a statewide average; coastal and higher-value properties routinely see far more. Individual retirees with paid-off coastal homes have reported premiums climbing from around $4,000–$5,000 a few years ago to $14,000, even $28,000 a year today. Property taxes are a second, compounding pressure: Florida’s homestead exemption and Save Our Homes assessment cap help long-term owners, but rising assessed values still push tax bills upward year over year, and none of the current relief proposals in the state legislature have passed as of this writing.
Between homeowners insurance, auto insurance, and property taxes, our own household is looking at something in the range of $20,000–$25,000 a year to stay in Florida — and that’s before groceries, healthcare, or anything else. We’re planning for the possibility of living to 90. Run that insurance-and-tax number out for another 20-plus years, with no reason to expect it gets cheaper, and it stops being an annoying renewal notice and starts being a structural threat to the retirement we’re trying to build.
Why Panama Changes the Math
This is the piece that made Panama, specifically, the answer for us rather than just “somewhere cheaper.” Panama runs on a territorial tax system: it taxes income earned inside Panama and nothing else. Social Security, 401(k) and IRA distributions, pension income, and investment income generated outside the country are not taxed by Panama at all — not partially exempted, not taxed at a reduced rate, simply outside the system. (You still file U.S. taxes as a citizen no matter where you live, but that’s a U.S. obligation, not a Panamanian one.)
Layer that on top of a genuinely lower cost of living — housing, groceries, and health insurance all run well below Florida prices, and we’ve documented specific numbers elsewhere on this site — and the combined effect is significant. Swap a $20,000–$25,000 annual Florida insurance-and-property-tax bill for Panama’s equivalent housing and insurance costs, which run closer to $3,000 a year in our own research and budgeting, and you’ve freed up a five-figure sum every single year for the rest of a multi-decade retirement. That’s not a lifestyle downgrade. For us, it’s the difference between a retirement budget that works and one that doesn’t.
This Is Household Math, Not a Universal Number
Our $20,000–$25,000 figure reflects our specific home, coverage levels, and coastal Florida location — yours will differ. The point isn’t the exact number; it’s that insurance and property tax exposure in a state like Florida is now large enough, and unpredictable enough, to belong in a serious retirement projection rather than a rough estimate.
Why Not Spain
We’d genuinely prefer Spain. We lived there, we loved it, and it’s where a real piece of our heart still is. But we ran the numbers honestly, and Spain works against the exact plan we’re trying to build in two specific ways.
First, cost of living and housing in the parts of Spain we’d actually want to live are meaningfully higher than Panama’s, which erodes the same savings we’re working this hard to protect. Second, and more decisively: Spain levies a wealth tax — Impuesto sobre el Patrimonio — on the worldwide net assets of anyone who becomes a Spanish tax resident, not just assets located in Spain. As of 2026, the national baseline exempts the first €700,000 of net wealth plus up to €300,000 for a primary residence, with rates then running from roughly 0.2% up to 3.5% depending on the autonomous region, and a separate national Solidarity Tax layered on top of net wealth above €3 million. Retirement accounts, investment portfolios, and other savings held anywhere in the world would count toward that calculation if we became Spanish tax residents.
Panama has no wealth tax. For two people trying to protect decades of retirement savings rather than shelter a fortune, that single structural difference outweighs how much we miss Spanish tapas and the pace of life there.
Building This Into Your Own Plan
None of this works as a last-minute decision. If there’s one thing the TIAA data and our own experience agree on, it’s that the damage from under-saving and the damage from choosing a retirement location under financial pressure both come from the same root cause: starting the real planning too late.
- Push your retirement contributions higher now, even if it changes your current lifestyle — the TIAA data says the alternative is regret, not comfort.
- Build a plan around the assumption that retirement may not be your choice or your timeline — a layoff or health event can remove years of planned contributions with no warning.
- Get real numbers on your current home’s insurance and property tax trajectory, not just today’s bill — ask what it’s likely to look like in 10 and 20 years.
- If relocating abroad is on the table, research the destination country’s tax treatment of foreign-source retirement income specifically — territorial systems like Panama’s and wealth-tax systems like Spain’s produce very different long-term outcomes for the exact same nest egg.
- Plan for a long life, not an average one. We’re budgeting to age 90. A cost structure that looks manageable for 10 years can become unsustainable over 25.
The Bottom Line
Three-quarters of today’s retirees wish they’d started saving sooner. Most people don’t get to choose exactly when retirement starts. And where you retire can be as large a lever on your long-term financial security as how much you saved to get there. We’re treating all three of those facts as true at the same time — pushing Kent’s 401(k) contributions to the legal maximum now, while it’s still fully our choice, and building a relocation plan to a country whose tax system and cost structure work with that savings instead of quietly eating it.
We’d rather feel the pinch of a maxed-out contribution today than read our own version of that TIAA survey in twenty years and recognize ourselves in the 76%.
Sources & Verification
- Reported: Tampa Bay Times, “Americans are retiring years earlier than planned. Most wish they had saved more,” August 2026, reporting on the TIAA Institute study.
- Official: TIAA Institute, “Bridging the Gaps in Retirement Expectations: New Evidence and Insights,” released July 22, 2026 (survey of approximately 1,591 U.S. adults ages 22–75).
- Official: IRS Notice 2025-67 and IR-2025-111 (Nov. 13, 2025) — 2026 401(k) employee contribution limit ($24,500) and catch-up contribution limits ($8,000 for age 50+; $11,250 for ages 60–63).
- Official: Panama’s territorial tax system — Panama taxes only Panama-source income; foreign-source pensions, Social Security, and retirement account distributions are not subject to Panamanian tax.
- Official: Spain’s Impuesto sobre el Patrimonio (wealth tax) — 2026 national baseline exemption of €700,000 plus up to €300,000 for a primary residence, with regional rates from approximately 0.2%–3.5%, applied to worldwide net assets for Spanish tax residents; a separate national Solidarity Tax applies above €3 million in net wealth.
- Reported: Florida homeowners insurance averaged approximately $8,292 annually in 2025 (an 18% year-over-year increase), per industry reporting; individual coastal and higher-value properties have reported premiums well above that average.
- Firsthand: Our own household finances — maximizing Kent’s 401(k) contribution since returning from Spain with depleted retirement savings; our estimated $20,000–$25,000 combined annual cost for homeowners insurance, auto insurance, and property tax on our current St. Petersburg home, versus an estimated $3,000 for equivalent Panama housing and insurance costs based on our ongoing relocation research.
- Not yet verified: Our Panama housing and insurance cost estimate is based on research and budgeting to date, not a full year of actual Panamanian bills. We’ll update this figure once we’re living there full-time and paying it directly.
Facts and figures in this article last verified: August 2026.
Not Financial or Tax Advice
We’re not financial advisors, accountants, or tax attorneys, and this article isn’t personalized advice. Contribution limits, tax rules, and insurance costs all vary by individual circumstances and change over time. Talk to a qualified financial planner and a tax professional familiar with both U.S. and your destination country’s rules before making decisions based on any of this.
More on Finance & Money in Panama
Brian & Kent
We’re a gay couple from St. Petersburg, Florida, researching and relocating to Panama in real time. Brian is pursuing a Pensionado visa; Kent is pursuing the Qualified Investor Visa. Everything on this site is from our direct experience — the prices, the observations, the mistakes.